In this world nothing can be said to be certain, except death and taxes.
– Benjamin Franklin
If you or a loved one don’t already have a will, and you’ve decided it doesn’t make sense*** for you to pay a few thousand to an estate planning attorney to create one, create one inexpensively with these tools.
Disclaimer: I am a financial advisor, not an estate planning attorney or any other type of lawyer. Consult your own legal counsel or do your own research to determine which estate planning solution is right for you.
Free estate planning docs
Freewill.com offers a will, revocable trust (only for California residents as of Oct 2026), advanced healthcare directive (with medical power of attorney baked in), and financial power of attorney docs completely free. Simply fill them out online, print, and get them signed/witnessed/notarized as needed. (In Washington state, for a will to be valid it must be
Freewill.com pushes charitable gifting, so if you’re not interested in that, just skip through those prompts and list your favorite humans as beneficiaries instead of your favorite charities.
Other online services
For those that live in California, paying $100 – $200 for Suze Orman’s package of estate planning documents is probably smart, since the revocable trust doc is designed with California’s probate process in mind.
Quicken Willmaker is another popular online will-making product at ~$200 or so. Rocket Lawyer is another one that some of my tech clients get for free via their employer
Trust & Will is a step up at the ~$600+ price point, but they claim to offer trusts as well as other docs.
Your employer’s legal benefit
White collar/tech employers often offer a ‘legal benefit’ you can enroll in (sometimes you must also elect to enroll your spouse) annually and then pay a small fee (~$200-$300/year) and get access to lawyers for several services, including the creation of estate planning documents. This can be a great way to get in front of a professional for a custom solution AND save money.
Urgency: do you need a will right now?
If you have minor children, are in poor health/elderly, or have a spouse or committed partner who is highly dependent on your income or assets, you need a will in place right away. With minor children, you also should have a recovocable or– in an ‘easy’ probate state like Washington– a testamentary (= baked into your will) trust. A trust specifies in advance who will manage your children’s assets should both you and/or your spouse pass away before they are responsible adults.
Any legitimate set of estate planning docs is better than none at all, so even if you decide you eventually want to pay an estate planning attorney to draft a more complicated set of docs that will take into account estate taxes, ‘blended families’ (children from prior marriages), or other complex situations, consider creating a basic will etc first, if it will take you a while to research and create your ‘best’ estate planning package later.
State and Federal estate taxes
Federal estate taxes currently have an exemption of $15 million per person, which can be combined for married couples. This means that couples with under $30 M won’t generally pay any Federal estate tax.
Many states, however, have estate taxes with much lower exemption limits. As of writing, California has no estate or beneficiary taxes, Washington state has one over $3 million (with NO ability to combine it with a spouse), and Oregon has one over $1 M (no ability to combine with spouse either.) Check the most recent info for your state as these things tend to change frequently.
Those with non-US connections can see the international link and search by country.
Note that any gifts you’ve given over the gift tax exemption limit– $19,000 per given per recipient in 2026– must be deducted from your lifetime Federal estate tax exemption (but NOT deducted from State estate tax exemptions, at least for Washington and Oregon.)
Other than reigning in your spending and making sure you have enough cash on hand for 3-12 months, here’s a quick AI-created (with Google Gemini)–but human-reviewed– checklist for what to do when you lose your job. The links are Washington state-specific for filing certain things like unemployment and subsidized health insurance.
Just remember: it could be worse!
1. File for Unemployment Benefits Immediately
Unemployment benefits are managed by the Washington State Employment Security Department (ESD). File during your first week of unemployment, as claims are not retroactive.
Social Security Number and full legal name as it appears on your SSN card.
18-month work history (employer names, addresses, federal tax ID numbers if available, and start/end dates).
Direct deposit details (routing and account numbers).
Crucial Next Step: Register for job search profile services via WorkSource Washington, which is a mandatory requirement to keep receiving benefits after applying.
2. Secure Health Insurance Coverage
You typically have 60 days from the date your employer-sponsored coverage ends (or the date of your layoff notice) to select a new health coverage path under a Qualifying Life Event.
Option A — COBRA (Employer Continuation):
Extends your existing employer network coverage for up to 18 months, but you typically pay 100% of the premium plus a 2% administrative fee. (Use your HSA to pay the premiums on COBRA if you want to. HSA also can pay Medicare premiums for ‘traditional’ Medicare Parts A, B, C and D.)
Watch for a COBRA election packet mailed directly by your former employer’s plan administrator or learn about federal regulations on the U.S. Dept. of Labor COBRA Guide.
Option B — Washington Healthplanfinder (State Marketplace & Medicaid):
Often significantly cheaper than COBRA due to income-based subsidies (Cascade Care) or eligibility for free/low-cost coverage under Apple Health (Washington Medicaid).
Before signing any severance agreements, review the terms carefully.
Final Paycheck Rights: In Washington State, employers must pay all earned, unpaid wages no later than the next regular payday. Check regulations and wage rules at the Washington State Dept. of Labor & Industries (L&I).
Severance Impact on Claims: Receiving a severance payout does not automatically disqualify you from ESD unemployment, but it must be reported.
Retirement Accounts: Contact your previous plan provider to review options for your 401(k) or 403(b) (e.g., leaving it in place, rolling over to a rollover IRA, or transferring to a future employer plan).
4. Explore Immediate Support & Career Resources
Career & Retraining Assistance: Access job boards, resume workshops, and potential worker-retraining grants through WorkSource Washington Locations.
Food & Utility Assistance: Apply for food assistance (SNAP/Basic Food) or emergency utility support using the unified portal at Washington Connection.
Not to be confused with the asset- and (very) income-limited SSI, SSDI provides disability payments for those who have earned enough social security credits to qualify and who apply and are approved.
Disclaimer: I am a financial advisor, not a tax accountant/CPA or lawyer. Check anything here with those folks for your specific situation and the current SSDI rules, which are always subject to change. This is a brief and not complete explanation of all the income-related SSDI rules
How does my non-SSDI income impact my SSDI benefit?
Unearned income (interest, capital gains, dividends) does not impact your SSDI benefit. However, wage income/income from active business DOES impact SSDI if you earn more than a particular amount per month.
9 months of trial work allowed
SSDI allows 9 months of trial work where you won’t lose any of your SSDI benefit no matter how much you earned in that month. If you earn more than $1,210 ($1,270 in 2027), that counts as one of your nine trial work months.
After trial work
Once you’ve hit nine months of trial work in a trailing 60 month period, you will receive NO SSDI benefit– it’s all or nothing– for any subsequent month where you earn more than the Substantial Gainful Activity amount. In 2026, that amount is $1,690. It will be $1,770 in 2027.
Small business details
If you are self-employed, you generally compute your earnings (NESE) as your average net profits for a given calendar/tax year. You can deduct your business expenses from your income for a given month when calculating your earnings for trial work or substantial gainful activity. You can also deduct the value of some non-expense items like help or materials you received for free due to your disability.
Screens, booze, weed, video games, gambling, members of the opposite sex: all are temptations that can be dealt with through strategies that make it easier to control ourselves and avoid risk.
Screen-based addictions
Control your phone
Read Digital Minimalism for motivation and how to think clearly about the pros and cons of our smartphone-based digital age. Jean M. Twenge is also a thoughtful critic.
Install Minimalist Phone first (Android and iOS), setting your machine to greyscale to make it more boring, and to a text-based list of apps. Only include apps in your ‘favorites’ list that are useful and necessary. Hide the distracting ones elsewhere.
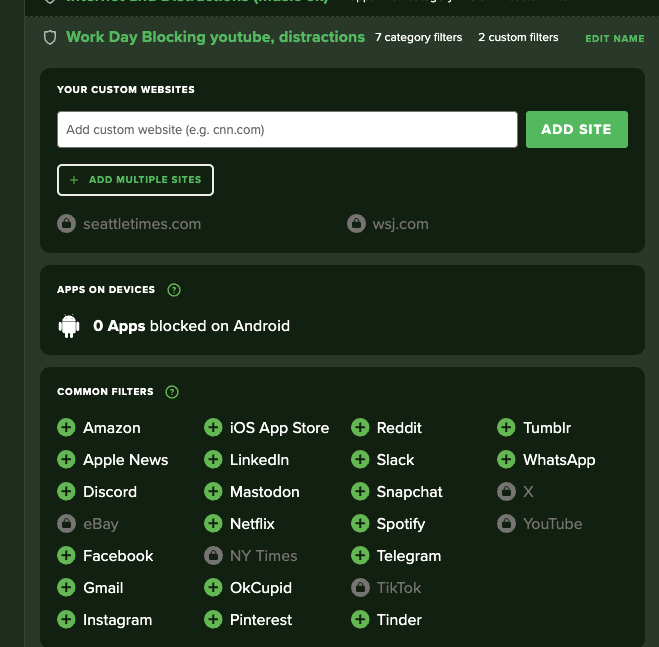
Next, install Freedom.to. This one is really a game-changer because you can set time-based sessions to block lists of apps and websites when you don’t want to use them. I do this at bedtime so I don’t stay up late wasting time on Youtube, etc. Set up lists and blocking sessions for any time of day so that you can focus on what you really want to do with your time.
I purchased the lifetime subscription option for both apps. It’s the best money I’ve ever spent on digital goods.
Remove nonessential notifications, pop-ups,
Use Minimalist phone to hide/block notifications for various services. I do this for text messages, social media, Amazon, and anything else where real-time notifications are completely unnecessary and an invitation to waste time.
I also use messages.google.com on my laptop to receive SMS messages on my laptop. You can do the same thing for WhatsApp, Facebook Messenger, Google Chat, etc. I like bucketing the hours I check nonessential texts to my work day hours on the laptop, unless I intentionally check them on my phone by opening the Messages app.
I have a separate app I use with people I message frequently and see in the physical world like family, neighbors, and close friends for ‘essential’ messages, and I keep notifications on for this app.
Tell people to call you if they need a response ASAP to make up for the fact that you won’t be constantly keeping up with text threads throughout the day. Speaking to someone is a much more fulfilling method of conversation anyway!
Control your laptop/ipad
Use Freedom.to on your laptop as well, including your work one. Set a specific list of filters for work day sessions.
Control your smart TV
Uninstall apps on your smart TV/Amazon Firestick and set up PINs/parental controls. Or, dump your remote control(s) or Firestick into a timed lock box that only unlocks on, say, weekends or whenever you allow yourself to use them.
Here’s some strategies (from AI) for removing Youtube– as an example– from your smart TV:
Non-screen vices
Strategies for moderation
Invest in timed lock boxes like those by Ksafe (I recommend a clear, large one to fit the most stuff), or this small one for phones/small things, that you can dump phones, video game controllers, drugs, alcohol, credit cards, snacks, or keys that go to locks– like if you wanted to lock your refrigerator, or a cabinet full of snacks, to avoid eating close to bedtime.
You set the timer and lock your stuff inside. Now you are forced to go without those things until the time is up and it unlocks. It’s a great way to space out your vices and only have them on weekends, say, or whenever works best for you.
Strategies for abstention
If you don’t ever want to do certain things, don’t let them inside your house or go near the places where you can do them! I have zero willpower if unhealthy food is around me, so I need to keep it out of my house in the first place: don’t go down the grocery store aisle where it lives, don’t put it in your shopping cart, and don’t bring it into your home. If it’s in your home, hide it somewhere hard to get at, or ask your spouse or roommates to lock it up where only they have they key.
Encourage guests or family members not to bring, say, desserts into your home without promising to take them away with them when they leave. Don’t go to the weed store or buy booze if you don’t want to use it/drink it. Stay away from bars or other places where you can buy booze if you don’t want to drink at all.
If you gamble, many casinos let you ‘self-ban’. Or, you can at least limit your habit by asking a casino not to let you cash checks, or leaving credit cards at home and only bringing the amount of cash you wish to lose with you.
Substitution of better alternatives
Substitute the things you don’t want for things that still scratch the itch. I don’t drink alcohol very much these days, but I’ve found non-alcoholic beer gives me a lot of what I love about beer: it’s cold, carbonated, tastes (mostly) like ‘real’ beer, and doesn’t give me a hangover or make me feel drowsy after having one. Plus, you can drink one in the car! Maybe a weekly poker game with your buddies would let you gamble at low cost without the casino’s cash-crushing rake.
If you’re trying to cut down on caffeine, whole bean decaf coffee is close to the real thing. If you’re missing the dopamine hit of entertaining screen time, try podcasts, radio plays, the radio, or reading a book/Kindle (get thee to a library!)
I love movies, but still find myself struggling at night after a long day of work & kids to have the attention span to watch one vs short-form garbage youtube content, so blocking youtube helps me have more ‘quality’ screen time. Better entertainment time is a win for me.
Avoid temptation and reduce risk with good habits
Sweet Jesus!
For risks that aren’t rooted in physical items or substances, avoid being in a risky situations. For couples, follow the Mike Pence/Billy Graham rule: don’t consume alcohol in a co-ed group– and certainly 1:1– without your spouse. Avoid 1:1 social meetings with members of the opposite sex– or at least, not in private. Pence’s rule was to avoid 1:1 meals with a woman, specifically, in addition to avoiding alcohol without his wife around.
Rules like these are the classic technique of working backwards: start from where you do not want to end up, think about how people commonly get there, and then avoid the behaviors that lead to it.
How do workplace extramarital affairs start? With private, 1:1 meetings, often with alcohol, and spending a lot of time with a member of the opposite sex that you’re attracted to. Avoid those meetings from the outset!
How many stories have we heard about men and women cheating on their spouses with close associates like campaign managers, personal assistants, or other confidants, or after a boozy outing with the ‘boys’ or ‘girls’ chatting up a member of the opposite sex in relative privacy?
How do people get DUIs? They drink too much and have access to their cars. A friend of mine who tends to over-drink when he goes out always makes sure to Uber to the bar. Because of this, he has no possible way to make his night worse by driving drunk, and simply Ubers back at the end of the night.
How do most people get hurt in motor vehicle accidents? By not wearing seatbelts, driving drunk (or getting hit by a drunk driver), speeding, or riding motor cycles (or at least, without proper safety gear and precautions like a helmet and tough clothes.)
How do people drown? By not wearing life jackets at all times (85-87% of people who drown were not wearing life jackets.) How do people get lost in the woods and die of exposure? By wandering off trails and failing to have the 10 essentials on them for every hike or backpacking trip.
How do people get hurt by violence? By being around violent actors: a domestic partner who has hit you or your child before, or threatened you with violence. Getting drunk around men (it’s usually men!) you can’t trust completely. Or by being in the middle of people who will behave irrationally: bars at closing time, street ‘takeovers’, while committing crimes or in a high-crime area (ex: inner city gas station) at a high-crime time (ex: late at night.)
Avoiding temptation and risk is much easier than resisting it right in front of you.